
Do Class 4 Shingles Lower Home Insurance Premiums in Minnesota

The catch is that Minnesota's strict contractor classification rules mean even subcontractors on a project need to be properly classified and insured. When you hire a licensed general contractor, they're responsible for managing that compliance across every trade on your job. That's a layer of protection you simply don't get with an unlicensed handyman on a complex project.
Yes, Class 4 impact-resistant shingles can lower your home insurance premiums in Minnesota, typically by 10% to 28% depending on your carrier and policy. We install these shingles on homes across the state, and our project managers walk every client through the insurance documentation process so they actually capture those savings. At NorBrook Construction, we've watched this question go from niche curiosity to one of the most common things homeowners ask us during roof consultations, especially after Minnesota's increasingly severe hail seasons. The math tends to work out strongly in favor of the upgrade, but the details matter: which shingles qualify, which insurers offer the best discounts, and whether your specific home and policy make it worthwhile. Here's what we tell our clients when they're weighing this decision.
The Impact of Class 4 Impact-Resistant Shingles on Minnesota Insurance Costs
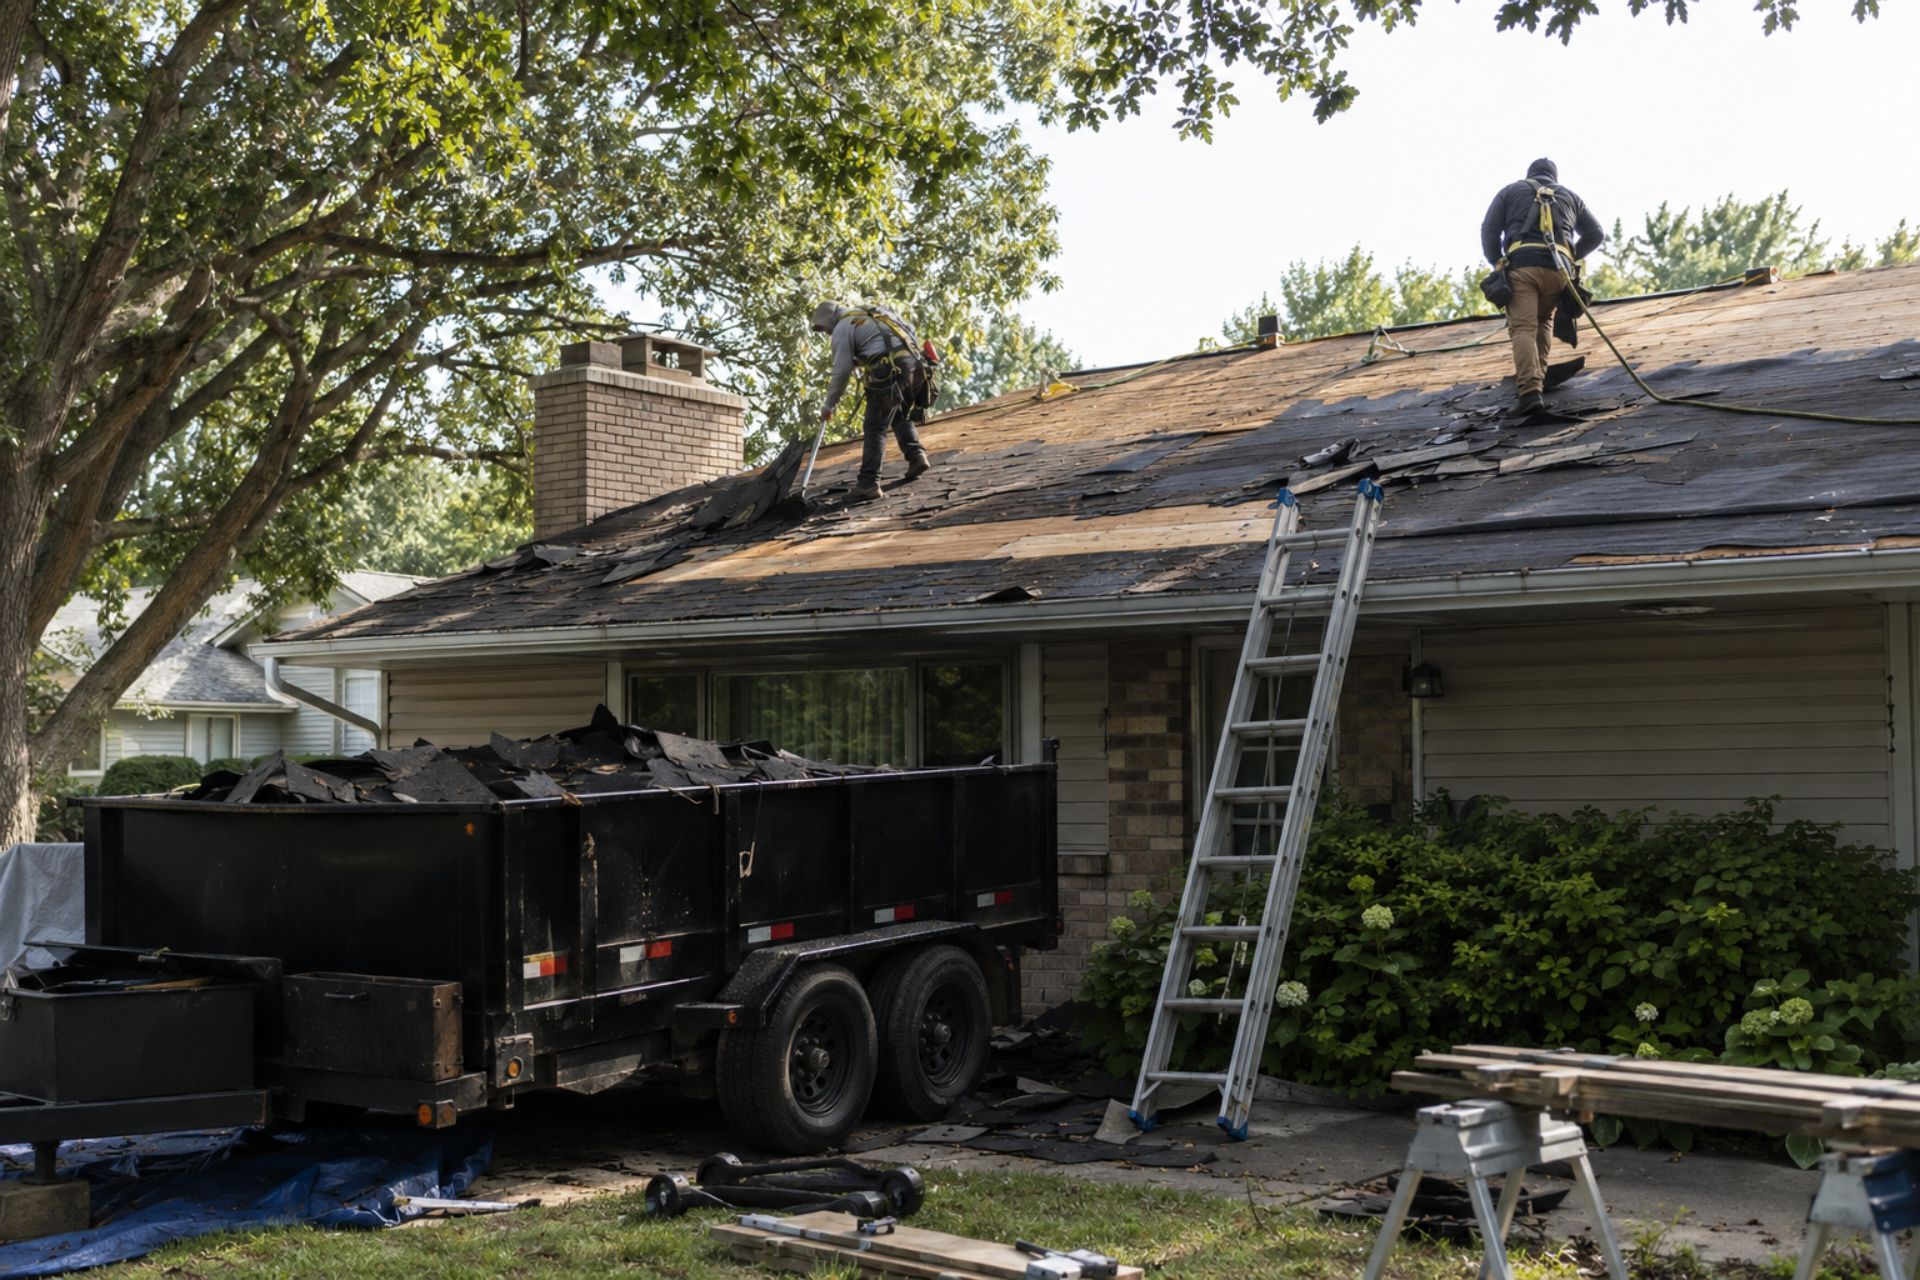
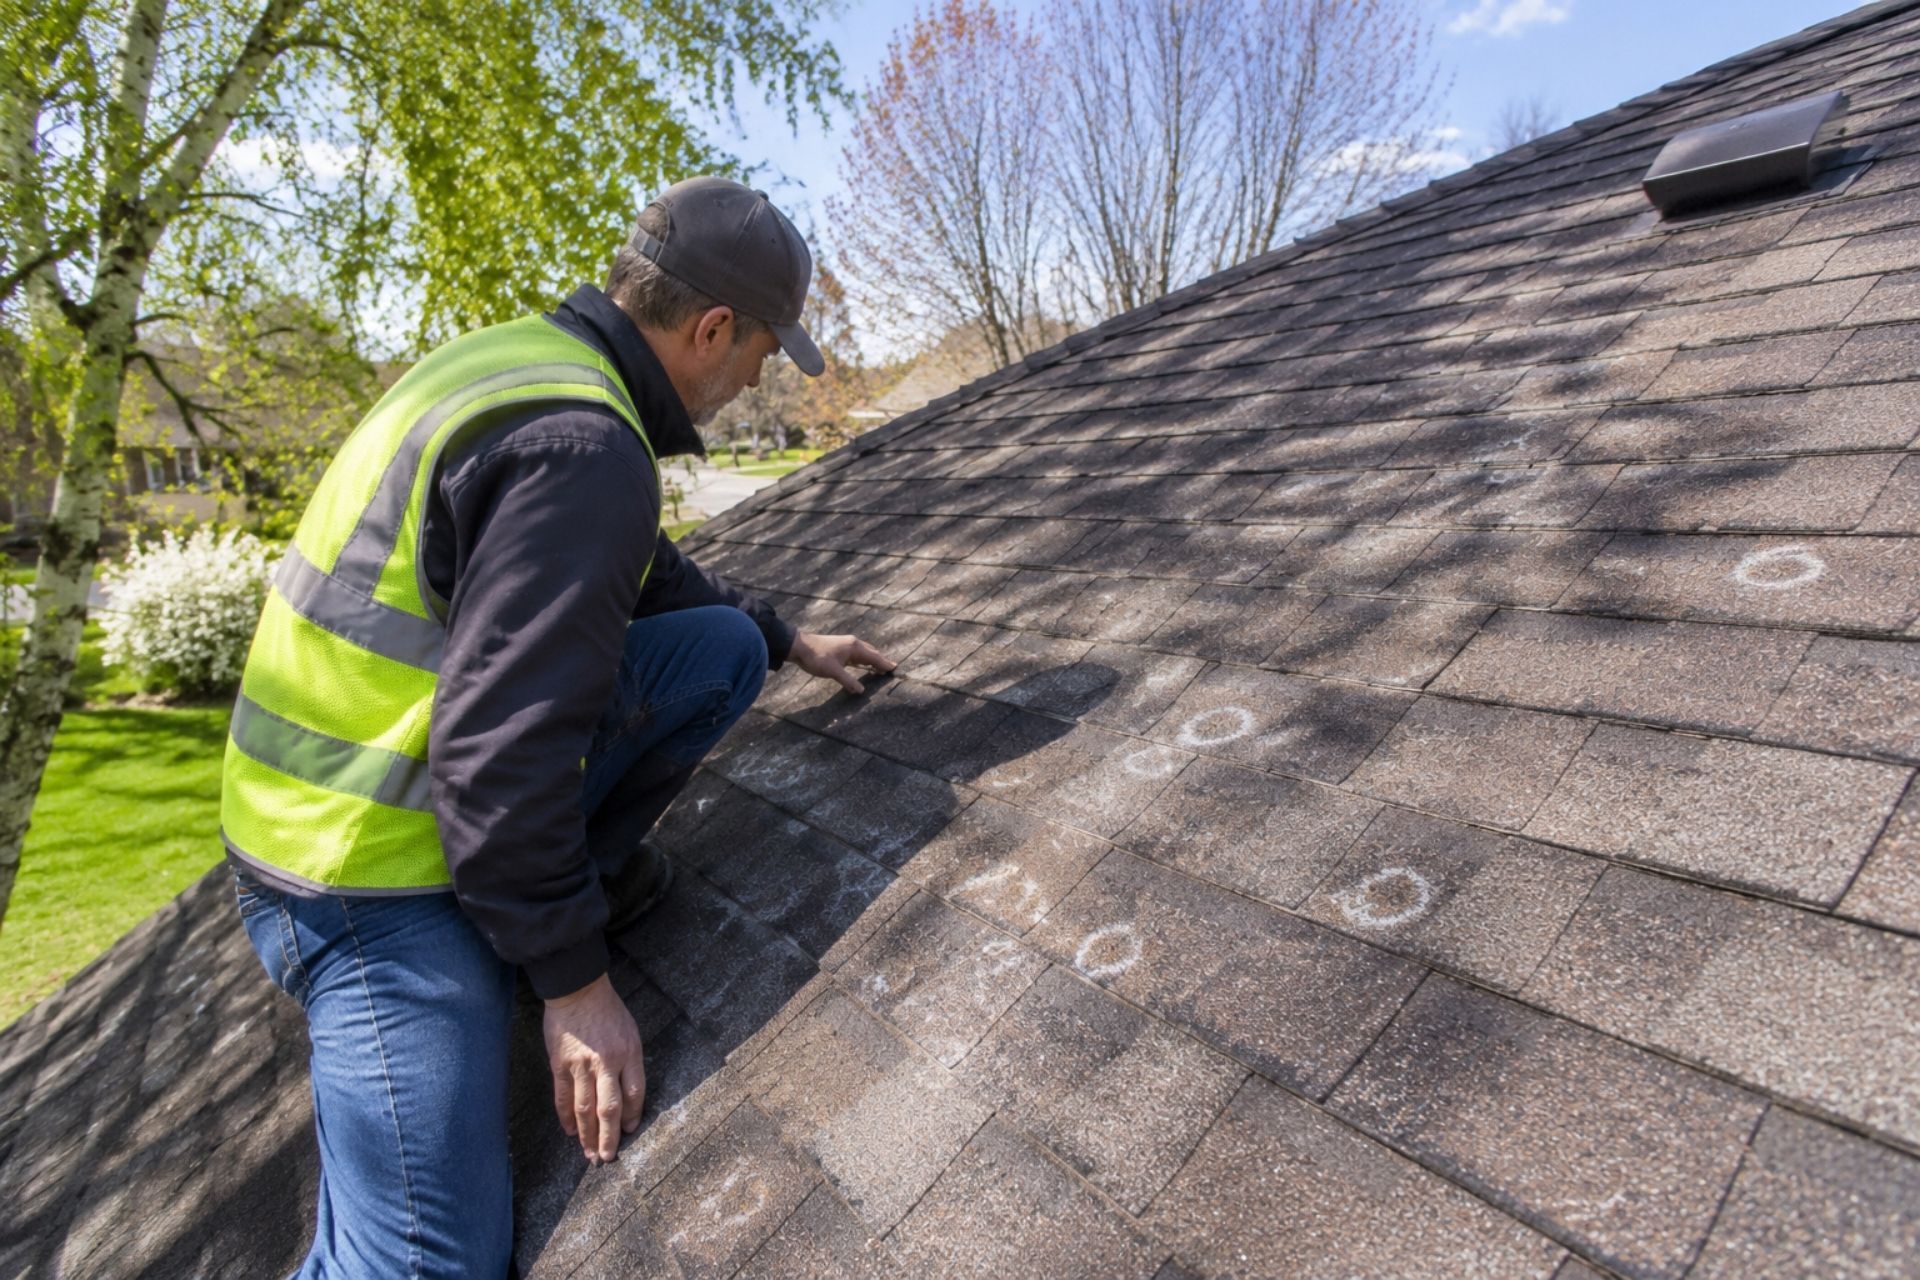
Minnesota sits squarely in the country's hail belt. Our crews see the aftermath every spring and summer: cracked shingles, dented gutters, and insurance claims that drive premiums up year after year. Class 4 shingles are designed to resist that damage, and Minnesota law actually supports homeowners who make the investment.
Under Minnesota Statute § 65A.298, insurance companies are legally required to provide premium discounts for residential properties that meet "FORTIFIED" standards, which includes impact-resistant roofing. That's not a suggestion or a marketing claim: it's state law. The practical result is that most major carriers operating in Minnesota offer measurable discounts when you can prove your roof meets the Class 4 standard.
The catch is that "discount" varies wildly. Some homeowners see 10% off their annual premium. Others see closer to 28%. The difference depends on your insurer, your location within Minnesota, your claim history, and the specific product installed. We always tell clients to call their insurance agent before committing to a roof replacement so they know exactly what savings to expect.
Understanding the UL 2218 Standard for Hail Protection
The Class 4 rating comes from UL 2218, a testing protocol developed by Underwriters Laboratories. During testing, a two-inch steel ball is dropped from 20 feet onto the shingle. To earn a Class 4 rating (the highest), the shingle must show no cracking, splitting, or fracturing after two impacts on the same spot.
That's a serious test. Standard architectural shingles fail it consistently. Class 4 products use modified asphalt formulations, polymer reinforcement, or rubberized compounds to absorb the impact energy. When we spec a Class 4 shingle for a Minnesota home, we're choosing products from manufacturers like CertainTeed, IKO, or Malarkey that have passed this protocol and carry the UL 2218 Class 4 designation on their product data sheets.
Your insurance company will specifically ask for proof of this rating. A shingle marketed as "impact-resistant" without the UL 2218 Class 4 certification won't qualify for the discount.
Estimated Premium Discounts from Major MN Carriers
Discount ranges shift from year to year as carriers adjust their risk models, but here's what we've consistently seen our clients report in 2025 and into 2026. State Farm and American Family typically offer discounts in the 15% to 28% range. Farmers and Allstate tend to land between 10% and 20%. Smaller regional carriers vary more, with some offering flat-rate reductions and others applying percentage-based discounts.
On a $2,400 annual premium (roughly average for a Minnesota single-family home), even a 15% discount saves $360 per year. Over a 25-year roof lifespan, that's $9,000 in premium savings alone, not counting the money you save by avoiding hail damage claims and the deductible expenses that come with them. Impact-resistant shingles can significantly reduce what homeowners pay for roof coverage over the life of the roof.
Why Minnesota Homeowners Hire NorBrook for Storm-Resistant Roofing
We're a licensed Minnesota residential building contractor (license BC80875, verifiable through the Minnesota Department of Labor and Industry). Our co-founders, the Norling brothers and Charlie Brookins, built NorBrook from our base in Maple Plain with a straightforward philosophy: treat every project like it's our own home.
For Class 4 shingle installations specifically, that means a few things. First, every job gets a dedicated project manager who handles communication from the initial estimate through final inspection. You'll get daily or weekly updates depending on the project scope. Second, our crews are led by OSHA 30 safety-certified leadership: co-founder Seth Norling holds the OSHA 30 certification, which matters when people are working on your roof in unpredictable Minnesota weather.
We're also EPA lead-safe certified (certification LFC-281), which is required for work on homes built before 1978. A surprising number of Minnesota homes fall into that category, and not every roofing crew carries this certification. When you call us at 763-237-5114, we'll tell you upfront whether your home requires lead-safe protocols and what that means for your project timeline.
Comparing Shingle Performance: Standard Architectural vs. Class 4 Impact-Resistant
The real question most homeowners wrestle with isn't whether Class 4 shingles are better: it's whether they're worth the price difference. That depends on your specific situation, but we can lay out the numbers clearly.
Standard architectural shingles cost less upfront and perform well in normal conditions. They're the default choice for most roof replacements. But in Minnesota, "normal conditions" include regular hail events, and standard shingles take visible damage from stones as small as one inch in diameter. That damage leads to insurance claims, which leads to higher premiums and potential non-renewal. Many Minnesota homeowners are finding that impact-resistant shingles pay for themselves through avoided claims and premium reductions within 5 to 8 years.
Cost Comparison Table and NorBrook Recommendations
| Feature | Standard Architectural | Class 4 Impact-Resistant | NorBrook Recommendation |
|---|---|---|---|
| Installed Cost (avg. MN home) | $9,000 - $13,000 | $12,000 - $18,000 | Class 4 for any home in a hail-prone county |
| UL 2218 Rating | Class 1 or unrated | Class 4 | Always verify the Class 4 designation on product data sheets |
| Insurance Discount | None | 10% - 28% annually | Call your agent before installation to confirm your specific discount |
| Typical Lifespan | 20 - 30 years | 25 - 35 years | The longer lifespan helps offset the higher upfront cost |
| Hail Damage Resistance | Cracks at 1" hailstones | Withstands 2" impacts | Critical in MN where 1.5"+ hail is common |
| Warranty Coverage | 25 - 30 years limited | 30 - 50 years limited | We help clients file warranty claims when needed |
| Break-Even Point | N/A | 5 - 8 years with insurance savings | Faster if you avoid even one hail claim |
The price gap between standard and Class 4 shingles has narrowed over the past few years as demand has increased and manufacturers have scaled production. On a typical 2,000-square-foot Minnesota home, the premium for Class 4 runs about $3,000 to $5,000 more than standard architectural. That's the number we use when helping clients calculate their break-even timeline.
Navigating the Insurance Certification Process in Minnesota
Getting the discount isn't automatic. You need documentation, and it needs to be correct. We handle this process regularly, so here's what to expect.
After we install Class 4 shingles, we provide a certificate of completion that includes the manufacturer name, product line, UL 2218 Class 4 rating, and the date of installation. Your insurance company will need this document, and some carriers also request the manufacturer's product data sheet showing the Class 4 test results. A few carriers send their own inspector to verify the installation before applying the discount.
The timeline matters too. Some insurers apply the discount retroactively to your policy renewal date; others only apply it going forward from the date they receive documentation. We always recommend submitting paperwork within 30 days of installation to avoid missing a billing cycle.
Submitting the Proof of Installation Form
Here's the step-by-step process our project managers walk clients through:
- We complete the installation and provide you with a detailed certificate listing the product name, UL 2218 Class 4 rating, and installation date.
- You contact your insurance agent or carrier and request their specific form for impact-resistant roofing discounts. Some carriers use a standard form; others have their own version.
- Fill out the form with the information from our certificate. If your carrier requires a contractor signature, we sign it the same week.
- Submit the form along with a copy of our certificate and the manufacturer's product data sheet. We provide all of these documents at project closeout.
Follow up with your agent 2 to 3 weeks after submission to confirm the discount has been applied to your policy.
If your carrier pushes back or claims they don't offer the discount, reference Minnesota Statute § 65A.298. That statute requires the discount for qualifying installations. We've had clients who needed to escalate this conversation, and the statute gives you real standing.
Long-Term ROI: Beyond Just Monthly Premium Savings
The insurance discount gets all the attention, but it's honestly only part of the financial picture. The bigger savings often come from what doesn't happen after you install Class 4 shingles.
A single hail damage claim in Minnesota typically runs between $8,000 and $15,000 for a full roof replacement. Your deductible on that claim might be $1,000 to $2,500, and many Minnesota policies now carry percentage-based wind/hail deductibles of 1% to 2% of the home's insured value. On a $400,000 home, that's a $4,000 to $8,000 out-of-pocket expense every time hail hits. Class 4 shingles dramatically reduce the likelihood you'll ever need to file that claim.
Avoiding Deductible Expenses and Claim History Surges
Here's what that means for you in real dollars. Every claim you file goes on your CLUE report (Comprehensive Loss Underwriting Exchange), which insurers use to assess your risk. Two hail claims within five years can trigger a premium increase of 20% to 40%, and some carriers will non-renew your policy entirely. We've talked to homeowners who faced serious coverage challenges after multiple storm claims and wished they'd invested in impact-resistant roofing sooner.
The math works like this: if Class 4 shingles cost you $4,000 more than standard, and they prevent even one claim that would have cost you a $2,500 deductible plus $500/year in premium surcharges for five years, you've already broken even. Factor in the annual insurance discount, and you're well ahead within the first few years.
Expert Answers: Frequently Asked Questions About Class 4 Shingles
Here are the follow-up questions we hear most often from homeowners after they've done their initial research.
Do Class 4 shingles look different from standard shingles? No. Modern Class 4 products come in the same color ranges, textures, and profiles as standard architectural shingles. Your neighbors won't know the difference unless you tell them. We carry samples from multiple manufacturers so you can match your home's aesthetic exactly.
Will my insurance discount apply if I only replace part of my roof with Class 4 shingles? Almost never. Carriers require the entire roof to be Class 4 rated. A partial installation won't qualify, and we don't recommend mixing shingle types on the same roof anyway: it creates inconsistent weathering and can void manufacturer warranties.
How long does a Class 4 roof installation take? For a standard single-family home, our crews typically complete the job in 2 to 4 days, weather permitting. The installation process is identical to standard shingles, so there's no additional labor time built into the project.
Can I get the insurance discount if I already have Class 4 shingles from a previous contractor? Yes, but you'll need the original installation certificate and product documentation. If you don't have those records, your insurance company may accept a roof inspection report from a licensed contractor confirming the product type. We do these inspections regularly.
Are Class 4 shingles worth it if I'm selling my home soon? They can be. Homes with documented impact-resistant roofing often attract buyers who understand the insurance and durability benefits. That said, if you're selling within a year, the ROI calculation is tighter. We'd recommend discussing your timeline with us before committing.
Do all Minnesota insurance companies offer the same discount percentage? No. Discounts range from about 10% to 28% depending on the carrier. We always recommend getting a written confirmation of the discount amount from your agent before scheduling installation.
Your Next Step with NorBrook
If you're replacing your roof anyway, or if your current shingles took damage in a recent storm, Class 4 impact-resistant shingles deserve serious consideration. The insurance savings are real, the protection is measurable, and the break-even timeline in Minnesota is shorter than almost anywhere else in the country because of our hail exposure.
We'd like to talk through your specific situation: your current insurance policy, your roof's condition, and whether the Class 4 upgrade makes financial sense for your home. Every project we take on gets a dedicated project manager who keeps you informed from the first conversation through final documentation. If you want to know exactly what a Class 4 roof would cost on your home and how much you'd save on insurance, Request a Free Estimate or call us directly at 763-237-5114. We'll give you honest numbers and a clear recommendation, no pressure.