
Minnesota homeowners file more hail damage roof claims than residents of nearly any other state, and the financial stakes keep climbing. Minnesota recorded the steepest home insurance rate increase in the country in 2025, with a 34% jump in a single year, driven largely by severe storm losses. That means getting your claim handled correctly isn't just about fixing shingles: it directly affects your premiums for years to come.
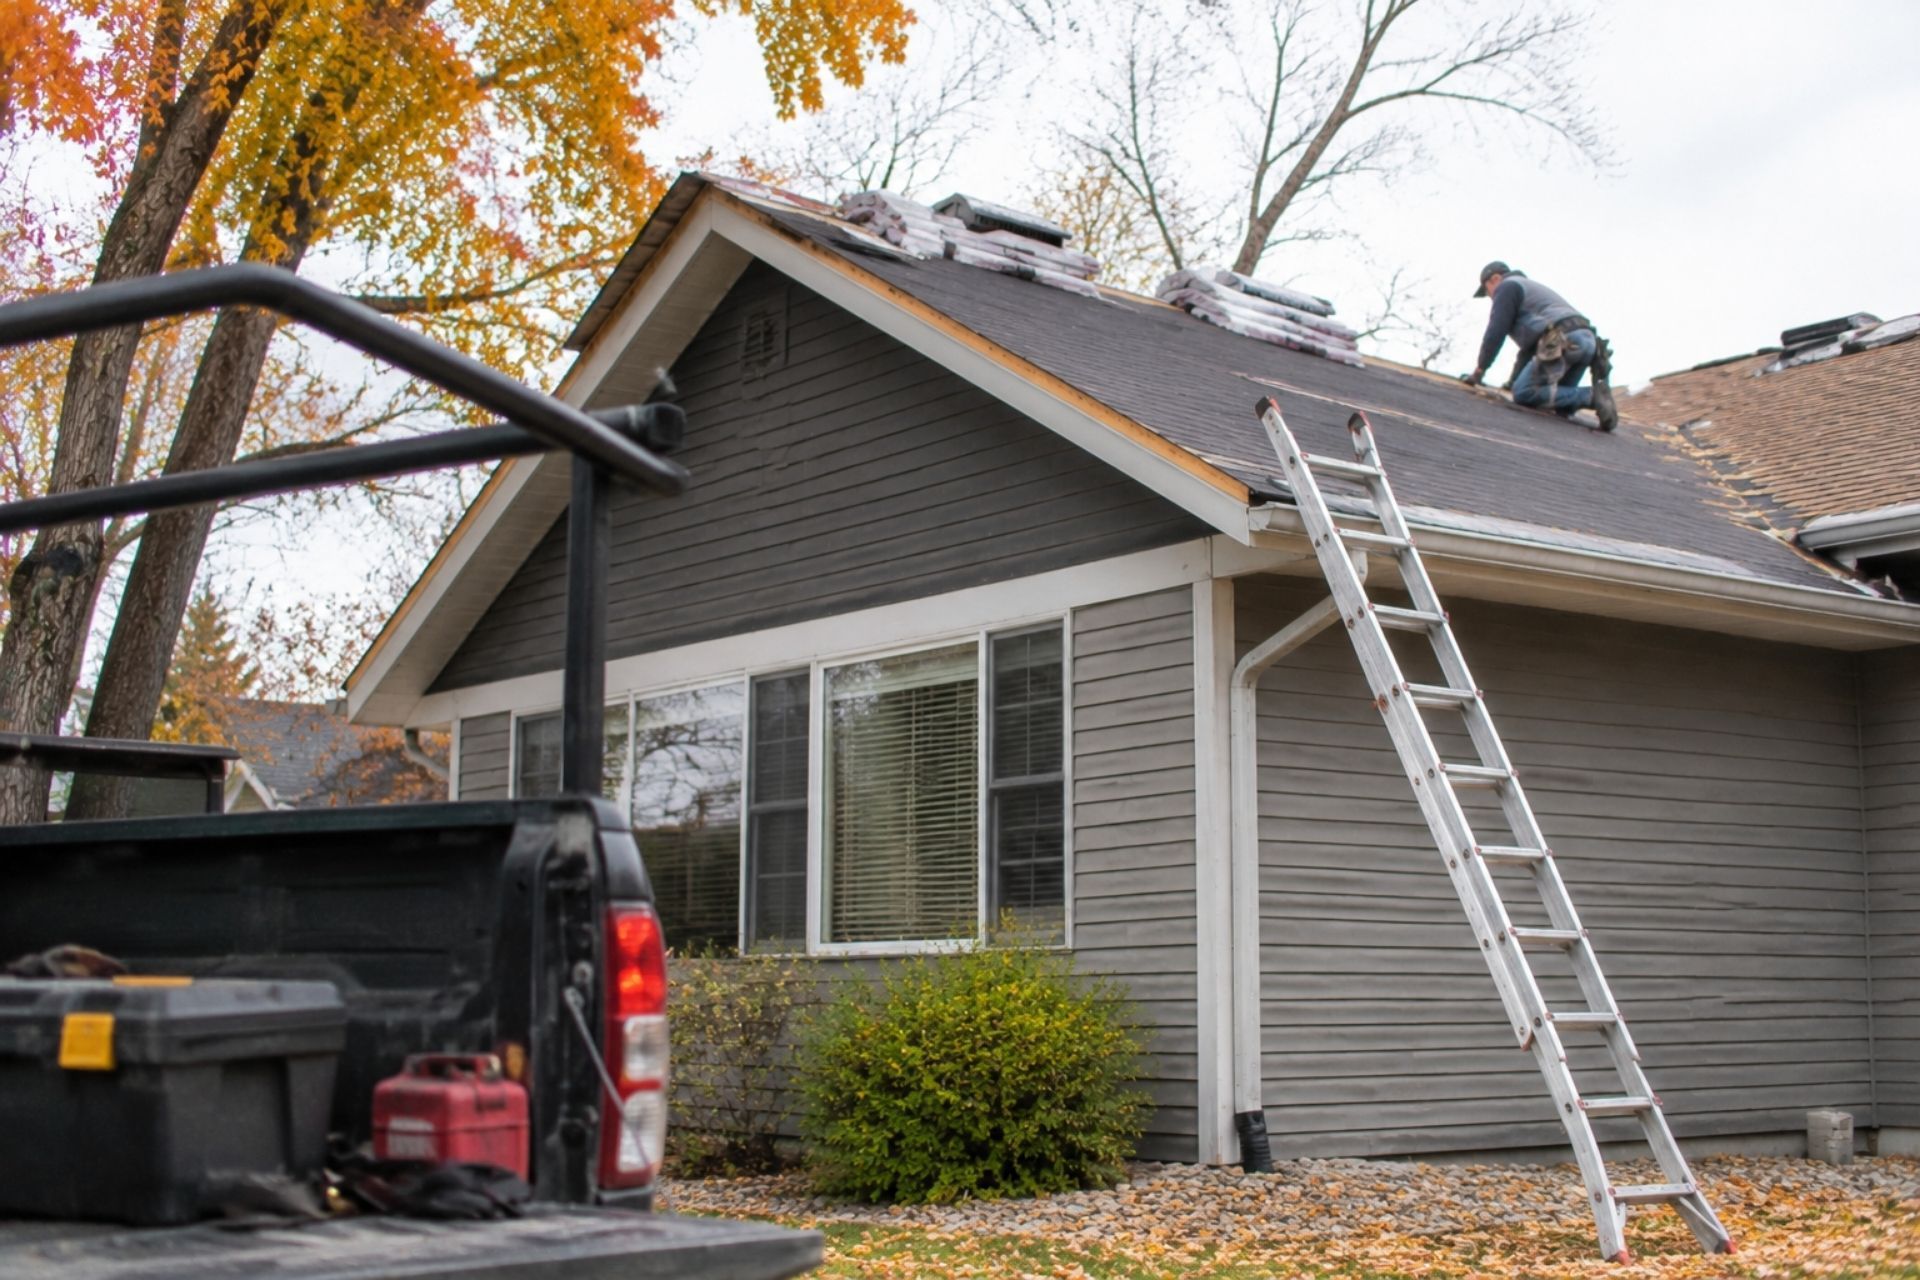
At NorBrook Construction, we've walked hundreds of Minnesota homeowners through the roof claim process from first inspection to final nail. Our crews, led by co-founders Seth Norling, Jordan Norling, and Charlie Brookins, handle storm restoration across the Twin Cities metro and beyond. We know what adjusters look for, what documentation makes or breaks a payout, and which mistakes cost homeowners thousands. This guide shares exactly what we tell our clients when hail hits their roof.
Understanding Minnesota's Hail Damage Landscape
Minnesota's geography puts it squarely in a corridor where warm Gulf air collides with cold Canadian fronts, producing hailstorms that can drop stones the size of golf balls. The 2023 and 2024 storm seasons alone generated billions in insured losses across the state, and 2025 continued the trend. That pattern isn't slowing down in 2026.
What makes Minnesota's situation distinct is the insurance response. Carriers have been
adjusting wind and hail coverage terms aggressively, shifting some policies from replacement cost to actual cash value or adding separate hail deductibles. Complaints to the Minnesota Department of Commerce about homeowner insurance have
roughly doubled since 2020, a sign that the claims process has become more contentious. Understanding your specific policy language before a storm hits is half the battle.
The Two-Year Statute of Limitations for MN Claims
Minnesota gives you two years from the date of the hail event to file a property damage claim. That sounds generous, but we've seen homeowners miss the window because they didn't realize their roof was damaged until a leak appeared 18 months later. By then, the insurer can argue the damage is from wear rather than a specific storm.
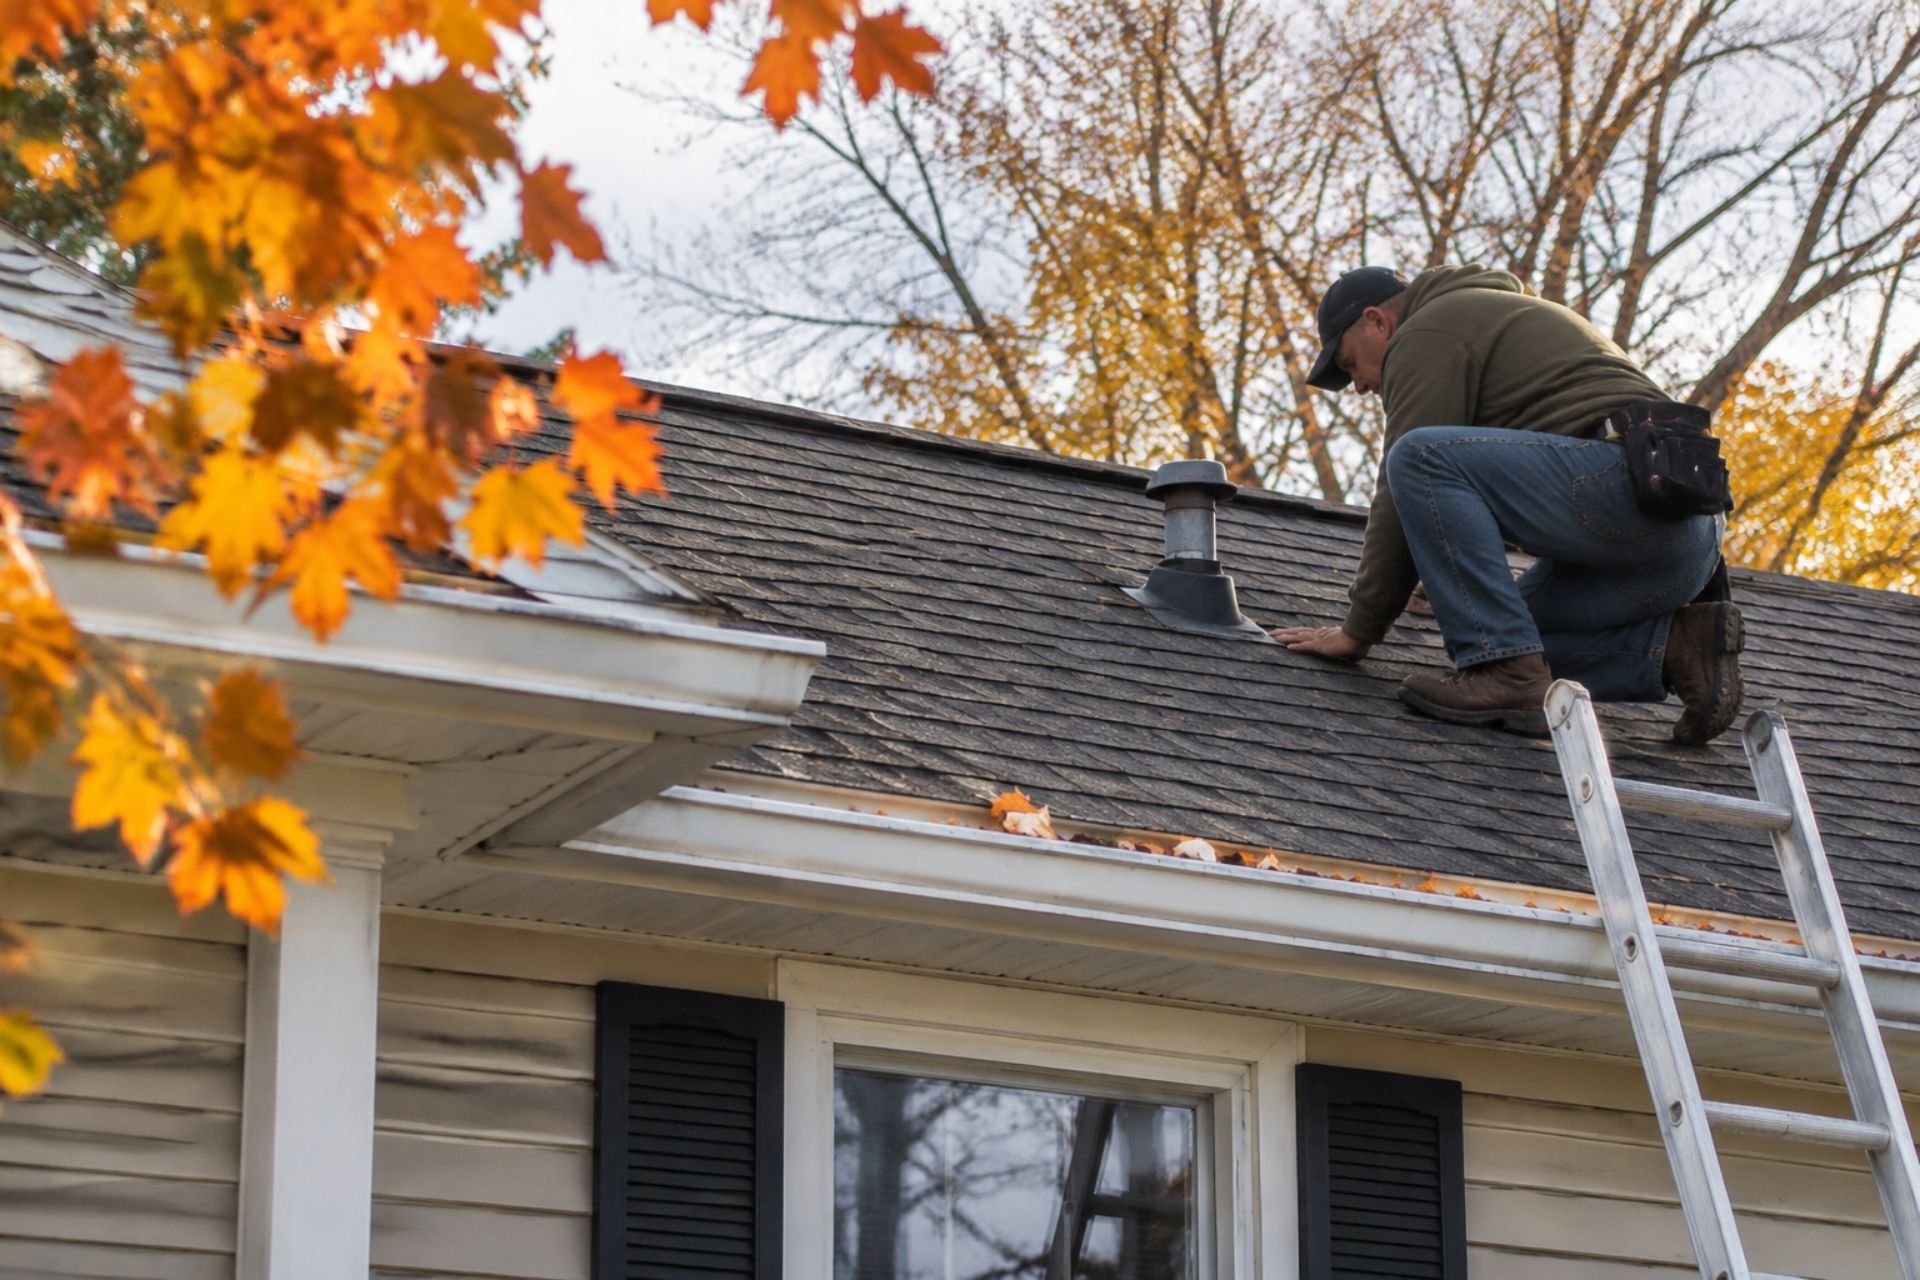
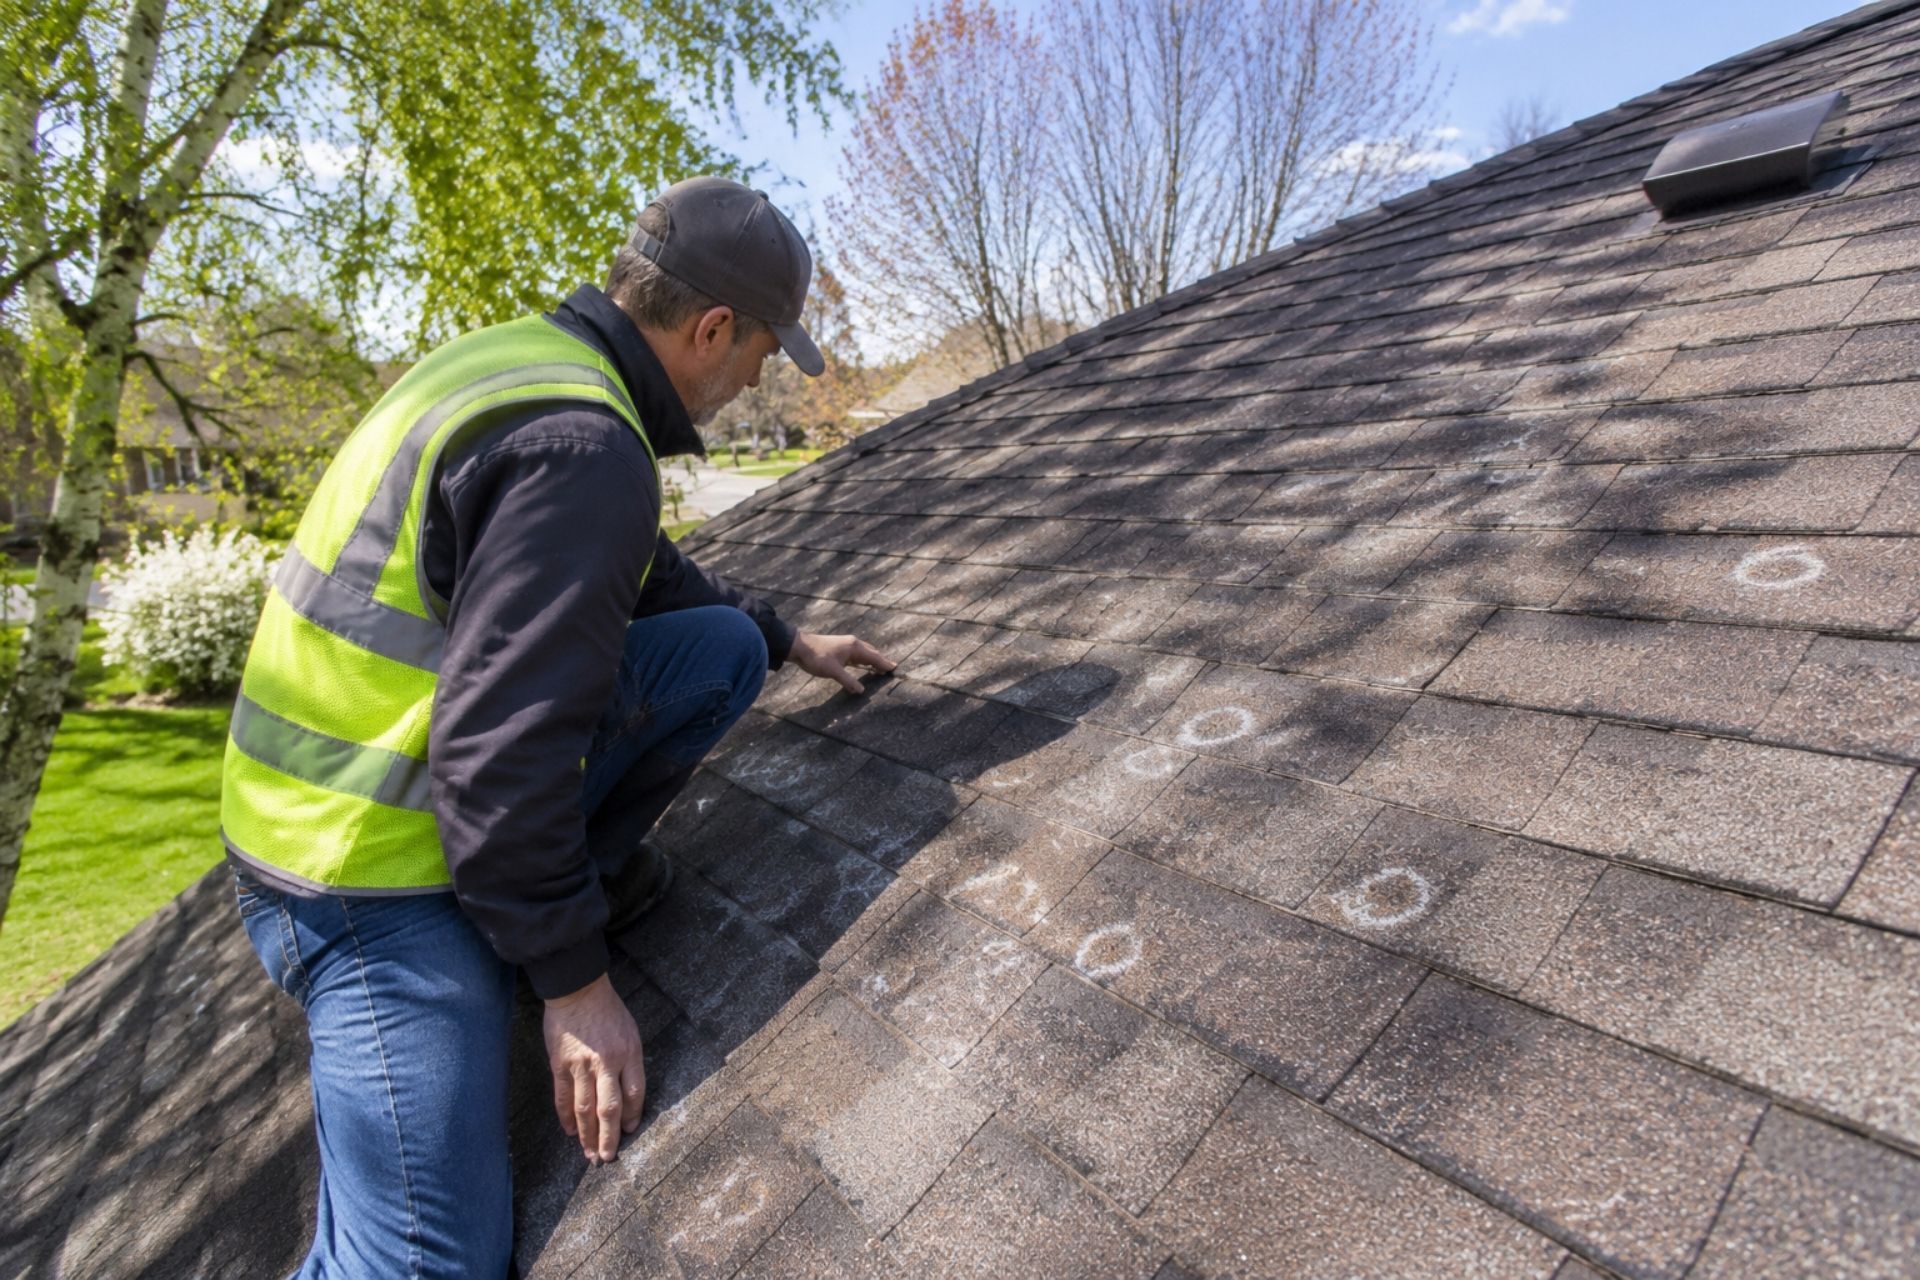
Our recommendation: get a professional inspection within 30 days of any significant hailstorm in your area, even if you don't see obvious damage from the ground. We provide free storm damage inspections and document everything with photos, measurements, and GPS-tagged reports. That documentation anchors your claim to a specific date and storm event, which is exactly what your insurer needs.
Identifying Functional vs. Aesthetic Hail Damage
This distinction matters more than most homeowners realize. Functional damage compromises the roof's ability to keep water out: cracked shingles, broken granule bonds exposing the fiberglass mat, dented metal flashing, or fractured ridge caps. Aesthetic damage is cosmetic: minor granule loss, small dings on gutters, or surface marks that don't affect performance.
Most Minnesota policies cover functional damage. Some cover both. The catch is that adjusters sometimes classify borderline damage as aesthetic to reduce the payout. When our project managers attend adjuster inspections, we bring manufacturer specifications showing the threshold where granule loss becomes functional. A shingle that's lost its granule layer over a hail strike point will fail years before its rated lifespan, and that's a functional problem regardless of whether it's leaking today.
The Step-by-Step Insurance Claim Process
Filing a hail damage roof claim in Minnesota follows a predictable sequence, but each step has pitfalls. Here's the process we walk our clients through:
- Document the storm: Note the date, approximate hail size, and duration. Check local weather reports and NOAA storm data for your zip code.
- Inspect your property: Look for dented gutters, cracked siding, damaged window screens, and marks on air conditioning units. These corroborate roof damage.
- Contact your insurance company: File the claim by phone, not just online. Get a claim number and the name of your assigned adjuster.
- Schedule a professional roof inspection: Have a licensed contractor inspect before the adjuster visits so you know the full scope of damage.
- Attend the adjuster meeting: Your contractor should be present. This is where claim amounts get determined.
- Review the estimate and scope: Compare the adjuster's line items against your contractor's findings. Discrepancies are common and negotiable.
- Authorize repairs: Once the claim is settled, sign a contract and schedule the work.
Navigating the Adjuster Meeting
The adjuster meeting is the single most important moment in your claim. This is where the scope of work gets defined, and whatever the adjuster writes down becomes the baseline for your payout. We always attend these meetings with our clients.
What we bring: a detailed damage report with close-up photos of every affected area, manufacturer data sheets showing impact thresholds, and measurements matching Xactimate software formatting (the same estimating tool most insurers use). When our numbers align with the adjuster's software, disputes shrink dramatically. We've found that homeowners who attend the adjuster meeting without a contractor present receive initial estimates 20-40% lower than those who have professional representation on the roof.
Comparing Material Options for Hail-Resistant Roofing
Once your claim is approved, you'll need to choose replacement materials. Minnesota's climate demands roofing that handles freeze-thaw cycles, ice dams, and yes, future hail. The average roof replacement in Minnesota runs between $8,000 and $15,000 for a standard home, but material choice can push that range in either direction.
| Material | Impact Rating | Typical Lifespan | Cost Range (per sq ft installed) | NorBrook Recommendation |
|---|---|---|---|---|
| 3-Tab Asphalt | Class 1-2 | 15-20 years | $3.50-$5.00 | Not recommended in hail-prone areas: saves money now, costs more in repeat claims |
| Architectural Asphalt | Class 2-3 | 25-30 years | $5.00-$7.50 | Our standard recommendation: best balance of cost, durability, and insurance compatibility |
| Impact-Resistant (Class 4) | Class 4 | 30-50 years | $7.00-$10.00 | Worth the upgrade if your insurer offers a premium discount (many MN carriers do, 10-28%) |
| Metal Standing Seam | Class 4 | 40-60 years | $10.00-$16.00 | Ideal for homeowners planning to stay 15+ years: highest upfront cost but lowest lifetime cost |
| Synthetic Slate/Shake | Class 4 | 40-50 years | $9.00-$14.00 | Great aesthetic option for historic homes or HOA requirements |
We install all of these systems and can help you calculate whether the insurance premium discount on Class 4 materials offsets the higher upfront cost. For most of our Minnesota clients, architectural shingles with a Class 3 or 4 rating hit the sweet spot.
Why Homeowners Trust NorBrook for Storm Restoration
We're not a storm-chasing outfit that showed up last week. NorBrook Construction is based in Maple Plain, Minnesota, and we've been building and restoring homes across the metro for years. Our Minnesota residential building contractor license is BC80875, verifiable through the Minnesota Department of Labor and Industry. We also hold EPA lead-safe certification (LFC-281), which is required for work on homes built before 1978, and our co-founder Seth Norling carries OSHA 30 safety certification.
Local Expertise and Safety Certifications
Being local means we know the specific hail patterns that affect different parts of the metro. Plymouth and Maple Grove get hit differently than Eagan or Woodbury, and we've restored roofs in all of them. Every project gets a dedicated project manager who provides regular updates and serves as your single point of contact through the entire claim and rebuild process.
Our crews don't subcontract storm work to whoever's available. The same team that builds our custom homes handles our roof restorations, which means the craftsmanship standard doesn't drop just because it's an insurance job. We treat every roof like it's on a house we built ourselves.
Avoiding Common Pitfalls in Minnesota Claims
The biggest mistake we see homeowners make is signing a contract before their claim is approved. Some contractors pressure homeowners into agreements that include assignment of benefits clauses, essentially signing over your insurance rights to the contractor. That limits your control and can create disputes between your contractor and your insurer that delay the entire project.
Another common error: accepting the first adjuster estimate without review. Insurance companies have
been changing coverage terms in ways that reduce payouts, including switching from replacement cost to actual cash value on older roofs. If your roof is more than 10 years old, check whether your policy has been modified. The Minnesota Department of Commerce has
issued specific guidance urging homeowners to review their wind and hail coverage annually.
The Danger of 'Storm Chaser' Contractors
After every major hailstorm, out-of-state contractors flood Minnesota neighborhoods with door-to-door solicitations. They offer to "handle everything" with your insurance company, often for suspiciously low prices. Here's what that usually looks like in practice: they collect your insurance payout, do the cheapest possible work with the cheapest possible materials, and disappear before the first Minnesota winter tests their installation.
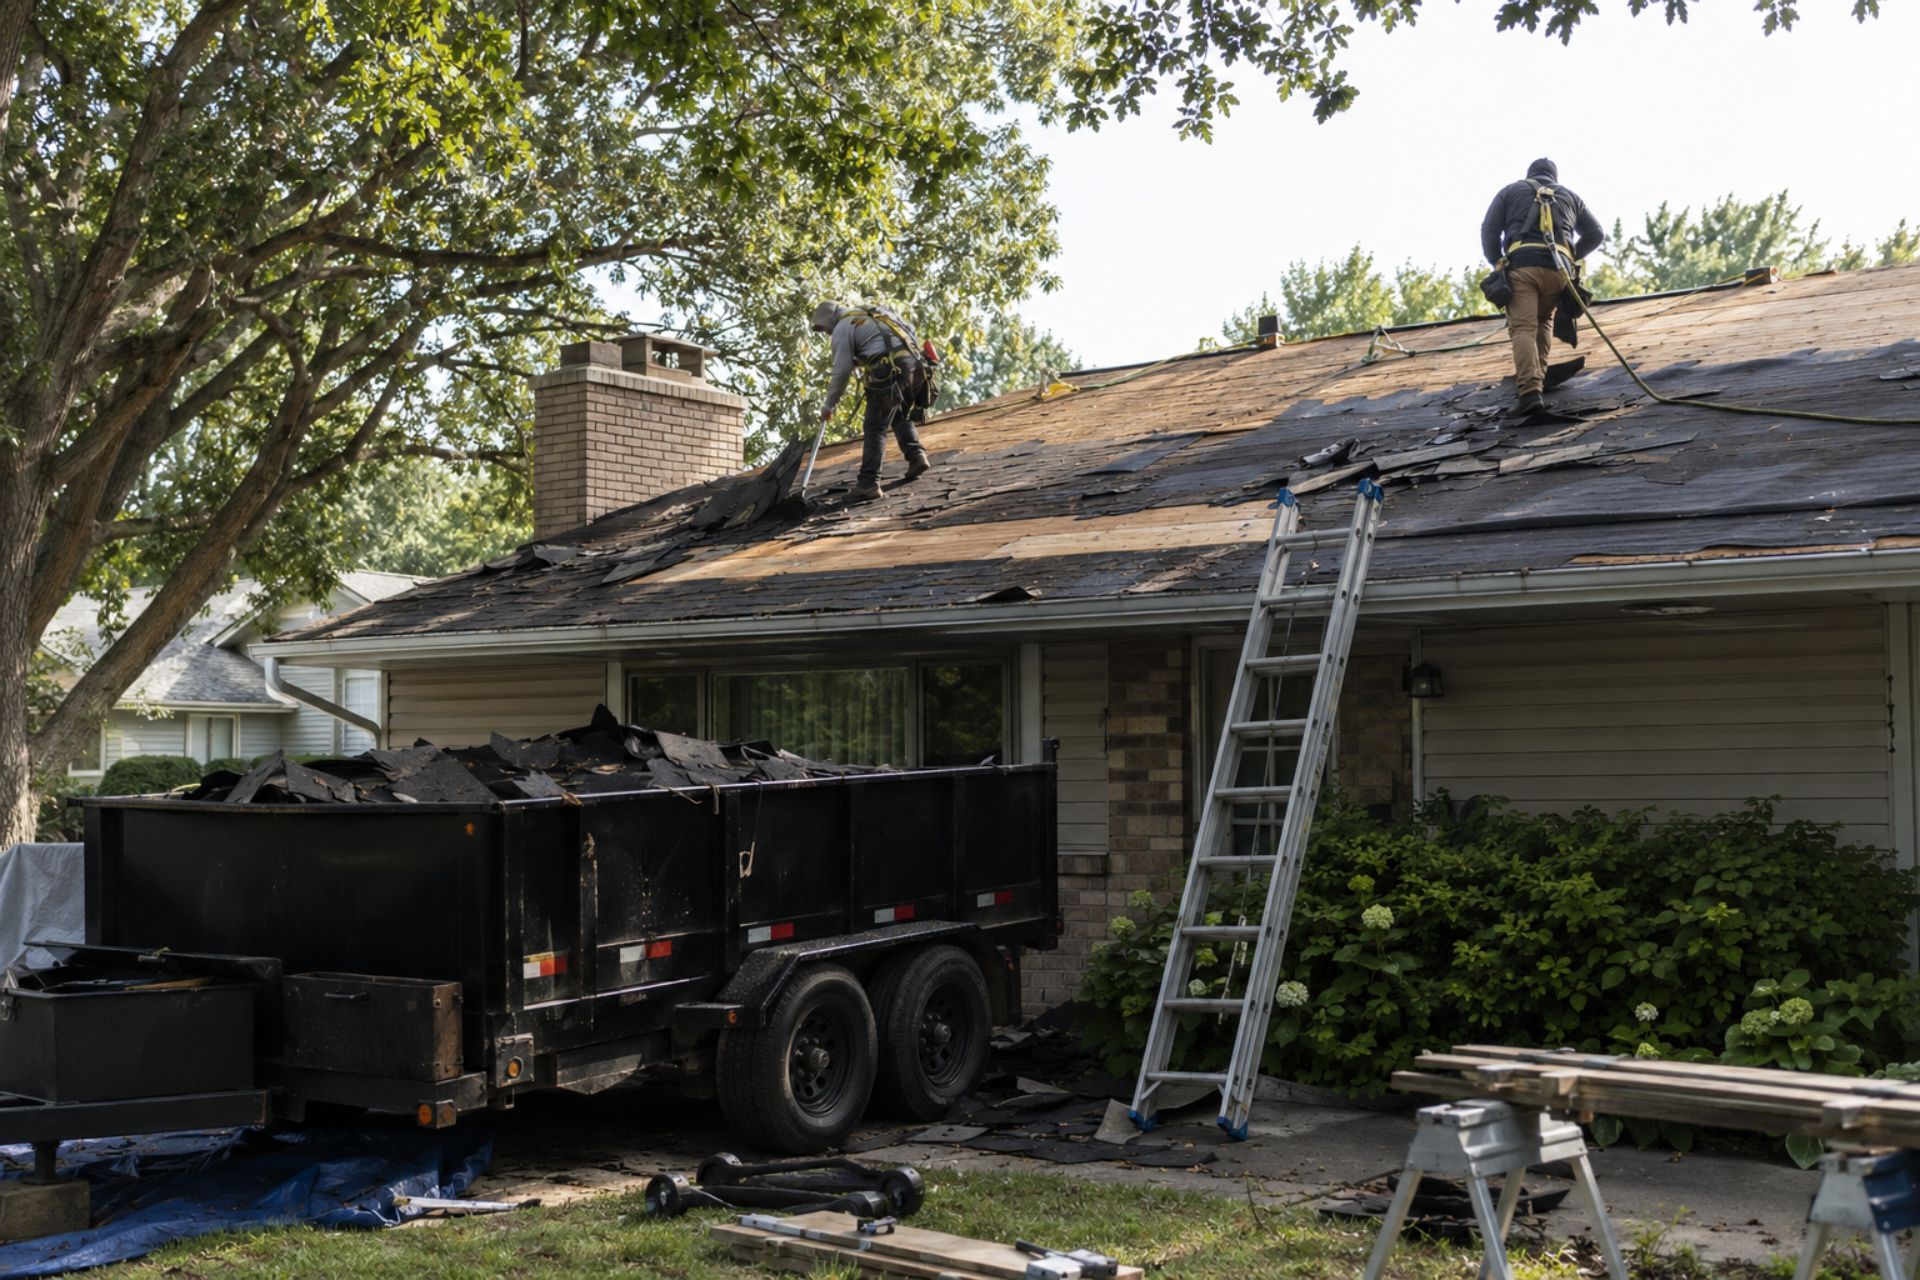
We've torn off and replaced roofs that storm chasers installed just one or two seasons earlier. Improper ice and water shield installation, missing starter strips, inadequate ventilation: these shortcuts don't show up immediately, but they cause leaks, ice dams, and voided manufacturer warranties. Always verify that your contractor holds a current Minnesota residential building contractor license and carries both general liability and workers' compensation insurance. If they can't produce those documents on the spot, walk away.
Expert Answers to Minnesota Hail Claims
How long after a hailstorm can I file a claim in Minnesota? You have two years from the date of the storm. That said, we strongly recommend filing within 60 days. The longer you wait, the harder it becomes to prove the damage is storm-related rather than age-related.
Will filing a hail claim raise my insurance premiums? It might. Minnesota insurers have been raising rates across the board due to storm losses, and a claim on your record can compound that. The flip side: ignoring real damage leads to leaks, structural rot, and far more expensive repairs down the road. We help clients weigh this decision honestly.
What if my adjuster's estimate seems too low? Request a re-inspection. You have the right to have your contractor present, and if the gap between estimates is significant, you can invoke your policy's appraisal clause. We've successfully supplemented dozens of claims where the initial estimate missed legitimate damage.
Does my homeowner's insurance cover the full roof replacement? That depends on your policy type. Replacement cost value (RCV) policies cover the full cost of new materials and labor. Actual cash value (ACV) policies deduct depreciation based on the roof's age. Check your declarations page or call your agent to confirm which you carry.
Can I choose my own contractor, or does the insurance company pick one? You always have the right to choose your own contractor in Minnesota. Your insurer may suggest preferred vendors, but you are not obligated to use them. We recommend choosing a locally licensed contractor who knows Minnesota building codes and climate conditions.
What's a Class 4 impact-resistant shingle, and is it worth it? Class 4 is the highest impact resistance rating under UL 2218 testing. These shingles withstand a two-inch steel ball dropped from 20 feet without cracking. Many Minnesota insurers offer premium discounts for Class 4 roofs, sometimes enough to offset the material cost difference within a few years.
Your Next Step with NorBrook
If hail has hit your roof this season, or you suspect damage from a previous storm, the clock is running on your claim window. We've guided Minnesota homeowners through every phase of this process: inspection, documentation, adjuster meetings, material selection, and installation. A dedicated NorBrook project manager handles your job from start to finish, keeping you informed and making sure nothing falls through the cracks.
Call us at 763-237-5114 or Request a Free Estimate to schedule your no-cost hail damage inspection. We'll get on your roof, document what's there, and give you an honest assessment of whether filing a claim makes sense for your situation. No pressure, no assignment of benefits tricks, no disappearing after the check clears. Just straightforward storm restoration from a contractor who'll still be in Maple Plain when the next storm rolls through.